Buying a first home in Jarrettsville is easier to manage when the process is broken into clear decisions: understand your budget, secure a strong preapproval, compare homes thoughtfully, and keep the contract timeline moving. This guide explains what happens between the first lender conversation and the moment you receive the keys, with practical questions to ask at each stage.
Start With a Budget That Accounts for the Whole Purchase
Before opening listing alerts or scheduling tours, take a close look at the monthly payment you can comfortably carry and the cash you want available for the transaction. A home payment generally includes principal, interest, property taxes, homeowners insurance, and, in some cases, mortgage insurance or association fees. It is also wise to reserve funds for moving, immediate maintenance, utility setup, and the small projects that often appear after closing.
For many buyers, the most useful number is not the largest amount a lender may approve. It is the payment range that leaves room for everyday priorities and the upkeep of the particular property you choose. Jarrettsville homes can vary considerably in lot size, age, systems, and features, so a budget that works for one property may feel different for another. Reviewing estimated taxes, insurance, utilities, and maintenance needs alongside the list price gives you a more complete picture.
Make a simple list of your non-negotiables and your preferences before you begin touring. Consider the number of bedrooms, work or hobby space, parking, outdoor maintenance expectations, property condition, and commute routes that matter to you. Separating needs from nice-to-haves helps you assess each home consistently instead of making a rushed decision based on one appealing feature.
A preapproval amount is a lending ceiling, not a spending requirement. Comparing estimated monthly payments at several price points can make your search feel more focused from the first showing.
Get Preapproved Before You Begin Making Offers
A lender preapproval is an early review of your income, assets, credit profile, and debts. It gives you an estimate of the loan program and purchase range you may qualify for, while also showing sellers that you have taken a meaningful financial step before submitting an offer. Ask your lender what documentation they need and whether a full preapproval, rather than a quick prequalification, is appropriate for your search.
Gathering documents ahead of time can reduce last-minute scrambling. Common requests include recent pay stubs, tax returns, bank statements, identification, and documentation for any funds being used toward the purchase. If your financial picture includes self-employment income, a recent job change, gifts, investments, or proceeds from another property, raise those details early so the lender can explain how they may affect underwriting.
It is also helpful to ask about loan options, projected interest-rate assumptions, down payment choices, lender fees, and potential closing costs. You do not need to become a mortgage expert overnight; you do need a clear estimate of the cash required before closing and an understanding of the conditions attached to your financing. Keep major credit changes, new debt, and unexplained account transfers to a minimum while your loan is in process.
Learn about buyer representation in Maryland
Tour Jarrettsville Homes With a Repeatable Process
Once your financing preparation is underway, the home search becomes more productive when you approach each visit with the same checklist. Notice the property’s condition, layout, storage, natural light, room dimensions, mechanical systems, driveway access, and the level of ongoing maintenance the home may require. Photos can introduce a home, but an in-person visit helps you understand how the spaces connect and what condition details deserve a closer look.
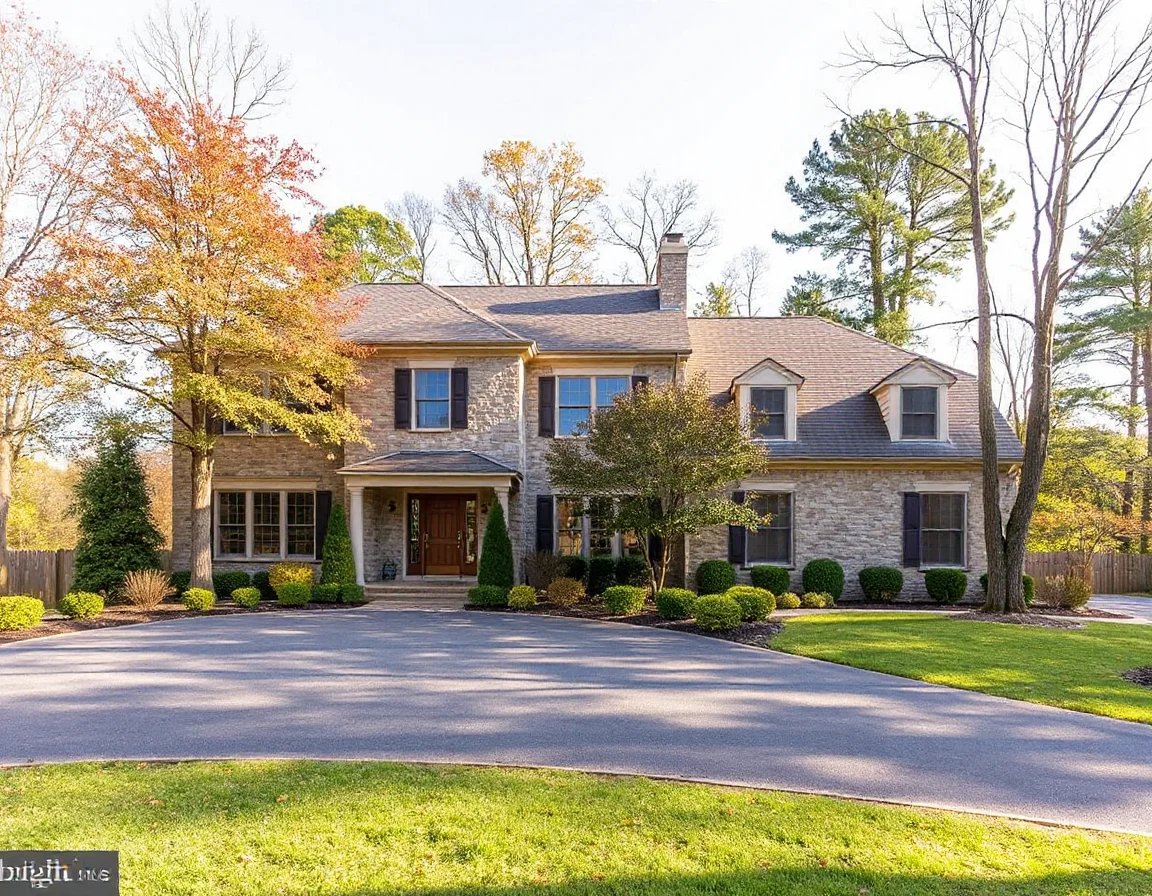
As you compare properties, look beyond surface finishes. A renovated kitchen may be meaningful, but so are the age and apparent condition of the roof, heating and cooling equipment, windows, well or septic components where applicable, drainage patterns, and any visible signs of deferred maintenance. Your agent can help you identify questions for the seller and determine which items may warrant professional evaluation during the inspection period.
Location research should be equally practical. Review travel routes at the times you expect to use them, observe road access and parking, and check publicly available information about property boundaries, zoning, taxes, and utility service. Nearby parks, local gathering places, recreation options, and the broader Harford County setting can all be part of your decision, but the right fit is based on your own daily routine and priorities.
When you find a home that stands out, compare it with recent nearby sales and active competition rather than relying on list price alone. A thoughtful market analysis can help you decide whether to move promptly, how to structure your terms, and where to draw your line before emotions enter the negotiation.
Write an Offer With Terms You Understand
An offer is more than a price. In Maryland, the contract can include financing provisions, inspection rights, appraisal considerations, settlement timing, deposit details, included items, and other negotiated terms. Each part affects your obligations and the overall strength of the offer, which is why first-time buyers benefit from reviewing the paperwork carefully before signing.
Your agent can explain the practical effect of the proposed terms and help you prepare a strategy based on the property, current competition, and your lending timeline. A seller may consider certainty of financing, flexibility around settlement, inspection terms, and the completeness of the offer alongside the price. There is no universal “best” offer structure; the goal is to present terms that are competitive while still protecting your ability to make an informed purchase.
The inspection period is a due-diligence window, not merely a repair wish list. Use it to understand the home’s systems, prioritize material concerns, and make decisions within the contract deadlines.
Move From Contract to Closing Without Losing Momentum
After an offer is accepted, the work shifts from shopping to coordination. Your lender continues processing the loan, the earnest money deposit is handled according to the contract, and inspections, appraisal, title work, insurance, and other tasks begin. Deadlines matter, so keep a calendar of key dates and respond quickly when your lender, agent, inspector, title company, or insurance provider requests information.
A professional home inspection provides an opportunity to learn about the property’s visible condition and systems. Inspectors may identify routine maintenance items, safety concerns, aging components, or conditions that merit further evaluation. Read the report carefully, ask questions, and work with your agent to determine whether a request for repairs or credits is appropriate under the contract. Not every finding requires negotiation, but every finding can help you plan responsibly.
The appraisal is another important checkpoint for financed purchases. The appraiser’s role is to provide an independent opinion of value for the lender, using the property and comparable sales. If appraisal questions arise, your lender and agent can explain the available next steps based on the loan type and contract terms. Continue avoiding new loans, large purchases, or financial changes until the transaction is complete.
Prepare for Closing Day and the First Weeks of Ownership
Near settlement, you will receive closing disclosures and final figures that outline your loan, projected payment, and closing costs. Review them promptly and ask questions about anything that differs from your expectations. You will also typically complete a final walkthrough shortly before closing to confirm the property is in the agreed-upon condition and that included items remain in place.
Closing day is the finish line for a detailed process, not the end of good planning. Save inspection reports, warranties, manuals, receipts, settlement documents, and service contacts in one accessible place. Change locks if appropriate, locate shutoffs, establish a maintenance schedule, and address the most time-sensitive projects first. With a realistic budget, strong guidance, and attention to each deadline, your first Jarrettsville home purchase can move from preapproval to keys with greater clarity and confidence.